Quick answer
Financing a purchase you can't pay off by the due date is the reason that isn't positive. That's when interest starts: $36.76 for one month on $2,000 at the Federal Reserve's 22.36% average for August 2026. Paid in full inside a grace period, the same purchase costs $0. Check your statement's Minimum Payment Warning box first.
Your personal finance quiz asks which reason for using a credit card to finance purchases isn't a positive one. Credit card financing is a way of paying for a purchase over time by carrying a card balance that earns interest. Everything below explains rules, and none of it is financial advice. Questions about your own account belong with the issuer's customer service line printed on your statement, and complaints about a card can be filed with the CFPB.
First come the quiz answer, the grace period and the formula for what carrying a balance costs. Then the minimum payment warning, three ways to pay down $2,000, 0% intro APR versus deferred interest, and where a payment above the minimum goes.
Key takeaways
- With a grace period, full payment by the due date costs $0 (October 2026).
- At the August 2026 average of 22.36%, $2,000 costs $36.76 in one month.
- Our example minimum-only plan took 139 months and $2,607.49 interest (October 30, 2026 test).
- Deferred interest added $155.48 of back interest on our $1,200 example (October 2026).
- Money above the minimum goes to the highest-APR balance first (Reg Z, October 2026).
Which is not a positive reason to finance purchases with a credit card?
The reason that isn't positive is financing something you can't pay off by the statement's due date. In plain words, it's spending money you don't have yet. It's also the one reason that switches on interest. The CFPB's page on credit card interest rates and APR states the free case. "On most cards, you can avoid paying interest on purchases if you pay your balance in full each month by the due date." Leave part of the balance unpaid past that date, and the APR goes to work on it. On our $2,000 example at the August 2026 average rate, a single month of that costs $36.76.
The positive answers on a quiz like this one, such as convenience, fraud protection and rewards, each rest on a rule or on paying in full. Under 15 U.S.C. 1643, your liability for unauthorized use of a lost or stolen card "is not in excess of $50" (as of October 2026). If someone steals only the account number, the CFPB's lost or stolen card answer says "you generally have no liability." It also notes, "Many cardholder agreements say you are not responsible for any charges in this circumstance." A wrong charge can also be disputed in writing, and our walkthrough on disputing a card charge you don't recognize covers that letter and its deadline.
Rewards follow the same rule. On our $2,000 example, one month of interest ($36.76) is more than the $20.00 a card paying 1% back (example rate, $2,000 x 1%) would return on the purchase. Our pieces on cards without an annual fee and what a travel card benefit is worth cover the perks side.
How the grace period keeps a purchase interest-free
So the free case depends on a grace period. The CFPB's page on the credit card grace period defines it as "the period between the end of a billing cycle and the date your payment is due." It also says card companies "are not required to give a grace period," though most do on purchases. Regulation Z, at 12 CFR 1026.5(b)(2)(ii), describes the same window. It's a period in which credit "may be repaid without incurring a finance charge due to a periodic interest rate." If your card's agreement doesn't offer one, a purchase can start costing interest from the day it's made.
You also get time to read the bill, and it's at least three weeks. Regulation Z says statements must go out "at least 21 days prior to the payment due date," and 15 U.S.C. 1666b puts the same 21 days in the statute.
Losing the grace period is where the costs begin. Per the CFPB, you're then "charged interest on the unpaid portion of the balance." New purchases are charged too, "starting on the date each purchase is made." Its tip goes further. If you pay in full some months and not others, you may lose the grace period "for the month that you don't pay in full and for the month after." Cash advances are different. Grace periods "typically apply only to purchase transactions," so their interest generally starts the day you take one. The CFPB's answer on interest for the month you pay adds that once a company starts charging interest, "it keeps charging interest until it receives your payment."
One old trick is gone. Since the CARD Act, 12 CFR 1026.54 bars interest from a lost grace period that's based on earlier billing cycles, or on any part you repaid in time. That's the practice once called double-cycle billing.
What carrying a balance costs, with the formula
Once a balance carries over, the APR sets the cost. The Federal Reserve's G.19 consumer credit release came out on October 7, 2026. It puts the August 2026 rate at 22.36% for credit card accounts assessed interest at commercial banks. Across all accounts, it's 21.19%.
The St. Louis Fed's FRED series for accounts assessed interest shows the same 22.36% for August 2026. We use the higher figure because it counts only accounts that paid interest. Your own APR is printed on your statement and in your card agreement.
Interest is charged by the day. The CFPB's daily periodic rate page says you divide the APR "by either 360 or 365, depending on the card issuer." Our example uses 365 days and a 30-day cycle:
Interest for one cycle = balance x APR / 365 x days in cycle
Example: $2,000.00 x 22.36% / 365 x 30 = $36.76
Daily rate: 22.36% / 365 = 0.06126% a day
That $36.76 is the simple version, and real bills run a little higher. The CFPB's answer on how interest is calculated says many issuers work from your average daily balance, day by day. The CFPB's daily periodic rate page adds that each day's interest "is then added to the previous day's balance." Compounding daily over the same 30 days on the same $2,000 comes to $37.08. That's 32 cents more. If the balance sat at $2,000 for a full year, simple interest alone would be $447.20 ($2,000 x 22.36%), before a single new purchase is added. For what the same money does when it's saved instead, our math on slow money and compound growth runs the formula the other way.
The minimum payment warning on your statement
Most monthly bills print this cost in a box, and a rule sets the words. Under 12 CFR 1026.7(b)(12), the box opens with the bold words "Minimum Payment Warning." Then it says that paying only the minimum each period means "you will pay more in interest and it will take you longer to pay off your balance." The statute behind it, 15 U.S.C. 1637(b)(11), words the warning as "Making only the minimum payment will increase the amount of interest you pay and the time it takes to repay your balance." It also lets the regulator set "such similar statement" after testing it on consumers, which is how the Regulation Z wording above came about.
Under the warning, you'll find two numbers for paying only the minimum: how long payoff takes and the total you'd pay. Time shows in months under 2 years and in whole years after that.
When payoff runs past 3 years, the box adds the payment that clears the balance in 36 months, its total cost and the savings. The CFPB's answer about the three-year box warns, "These amounts are calculated based on your current balance and do not take into consideration any future purchases."
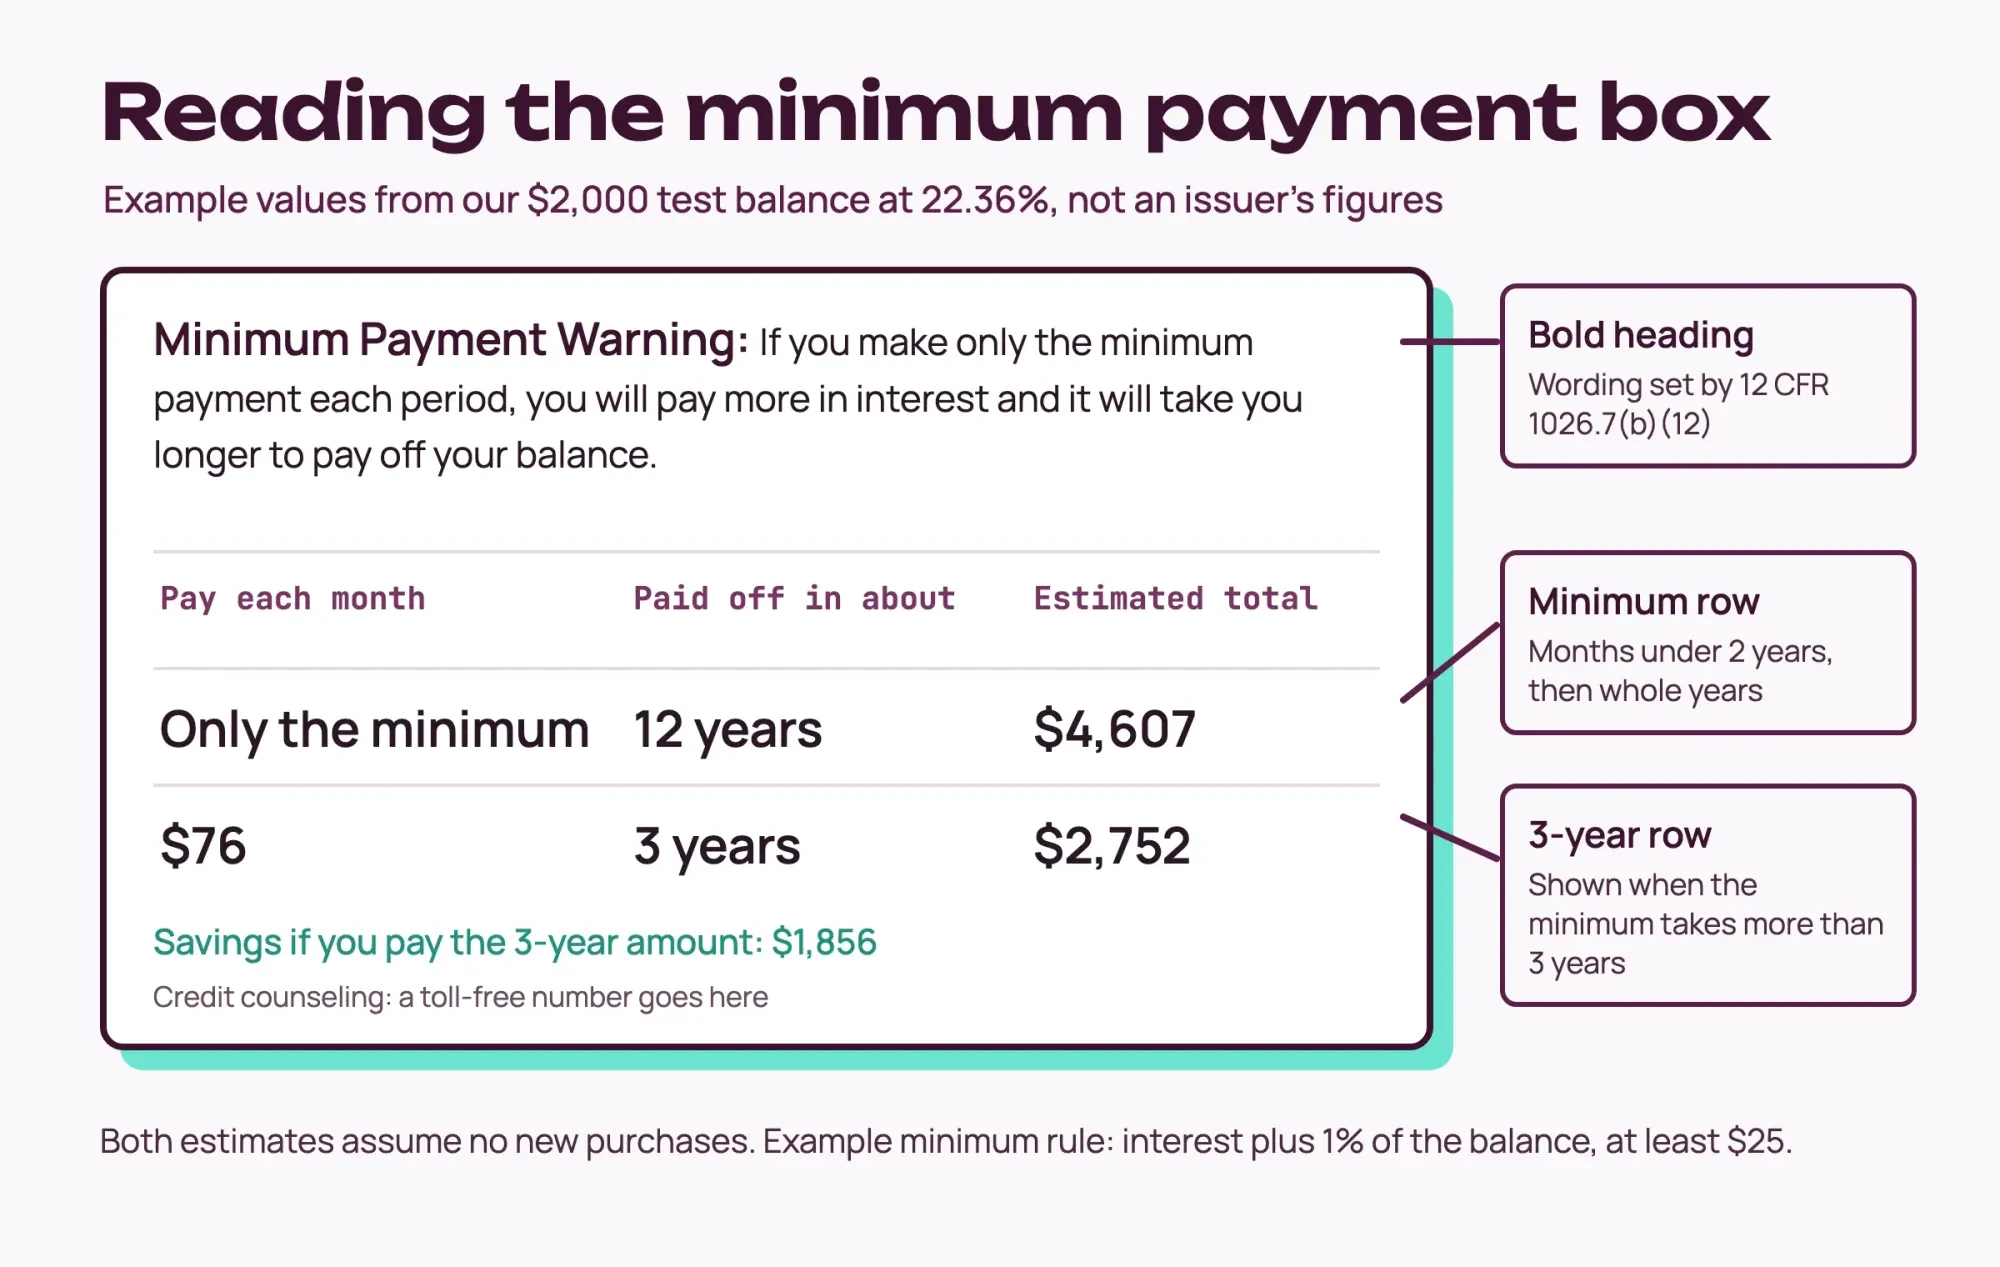 Drawn by us: heading quoted from 12 CFR 1026.7(b)(12); the values are our test results for a made-up $2,000 balance at 22.36%, not an issuer statement.
Some bills skip the box legally. The rule exempts charge cards paid in full each cycle, bills after two cycles paid in full or at zero, and any cycle where the minimum clears the balance.
There's a worse case, and it gets its own wording. If the minimum won't even cover the interest, the box must say "we estimate you will never pay off the balance shown on this statement." The reason follows: "your payment will be less than the interest charged each month."
The box also lists a toll-free number. Through it, the issuer must name at least three credit counseling groups approved by the U.S. Trustee or a bankruptcy administrator.
Three ways to pay down the same $2,000
Those box numbers come from a formula, so we ran our own on one balance. Each row starts at $2,000 and 22.36%, with no new purchases.
| In full by the due date, with a grace period | 1 | $0.00 | $2,000.00 |
| Minimum only (first payment $56.76) | 139 | $2,607.49 | $4,607.49 |
| Same payment for 36 months ($76.44) | 36 | $751.65 | $2,751.65 |
| Fixed $100 a month | 26 | $515.99 | $2,515.99 |
Look down the interest column first. The minimum rule here is our example: interest plus 1% of the balance, with a $25 floor. Real issuers set their own, so your box will differ. Paying only our example minimum each month cost $2,607.49 over 139 months, more than the $2,000 balance itself. A steady $100 a month cleared it in 26 months for $515.99. The 36-month row is the one a statement box would show, and it saved $1,855.84 against the minimum. At the start, the 36-month row asks for $19.68 a month more than the example minimum ($76.44 minus $56.76). That gap is what the $1,855.84 of saved interest rests on.
What we tested
Our test ran on October 30, 2026: a small Python payoff calculator worked through made-up balances at the August 2026 rate. A browser page on 127.0.0.1 then redid the four payoff rows in JavaScript from the same inputs. All 12 values matched. Three of them belong to the simple paid-in-full row. The model skips daily compounding, and its minimum rule isn't any issuer's.
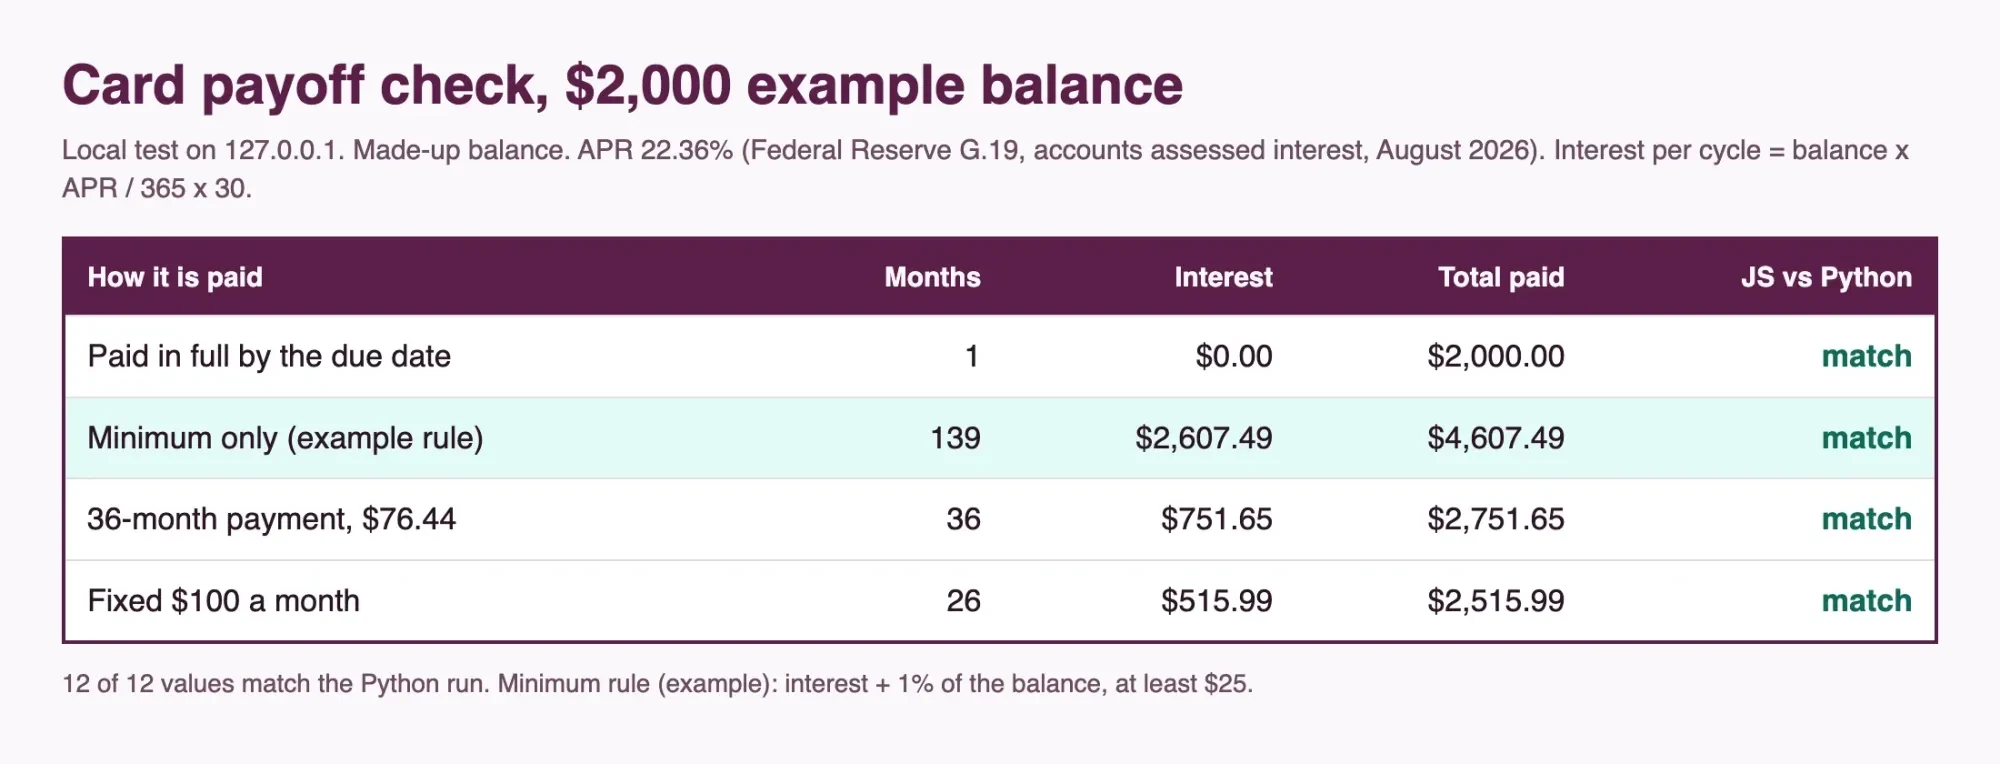 Screenshot: our payoff checker on 127.0.0.1, October 30, 2026; made-up $2,000 balance at 22.36% (Federal Reserve G.19, August 2026).
0% intro APR or deferred interest?
Store and card promos often sound alike on a checkout screen, but the federal rules split them into two very different deals. Regulation Z's ad rule, 12 CFR 1026.16(h), covers deferred interest. They're finance charges a consumer "is not obligated to pay" if the balance is "paid in full by a specified date." An ad that says "no interest" for such a plan must also say "if paid in full." A 0% intro APR works differently. The rate itself is zero for the period, so nothing builds up in the background. Those three words are what the rule makes a deferred interest ad show beside "no interest."
The CFPB's answer on deferred interest plans explains the catch. If you miss the deadline, or are "more than 60 days late in making a minimum payment," interest comes back. "Usually, the interest is calculated based on the balance you owed in each month since you first made the purchase."
In the CFPB's words, "Your minimum payments probably won't be enough to pay off the entire balance by the end of the deferred interest period." The end date sits on "The front page of your bill," which may differ from your usual due date.
Here's one purchase both ways. A $1,200 example purchase on a 12-month promo, paid down $90 a month, leaves $120.00 at month 12 under either kind. With a 0% intro APR, interest starts only on that $120.00, about $2.21 in the first cycle at 22.36%. With deferred interest, our calculator added back $155.48 for all 12 months of balances. That figure is the sum of the 12 monthly balances, $8,460, times 22.36% / 365 x 30. The next bill's interest came to $157.69, while paying $100.00 a month from the first bill would've cleared the purchase on time with no interest owed at all.
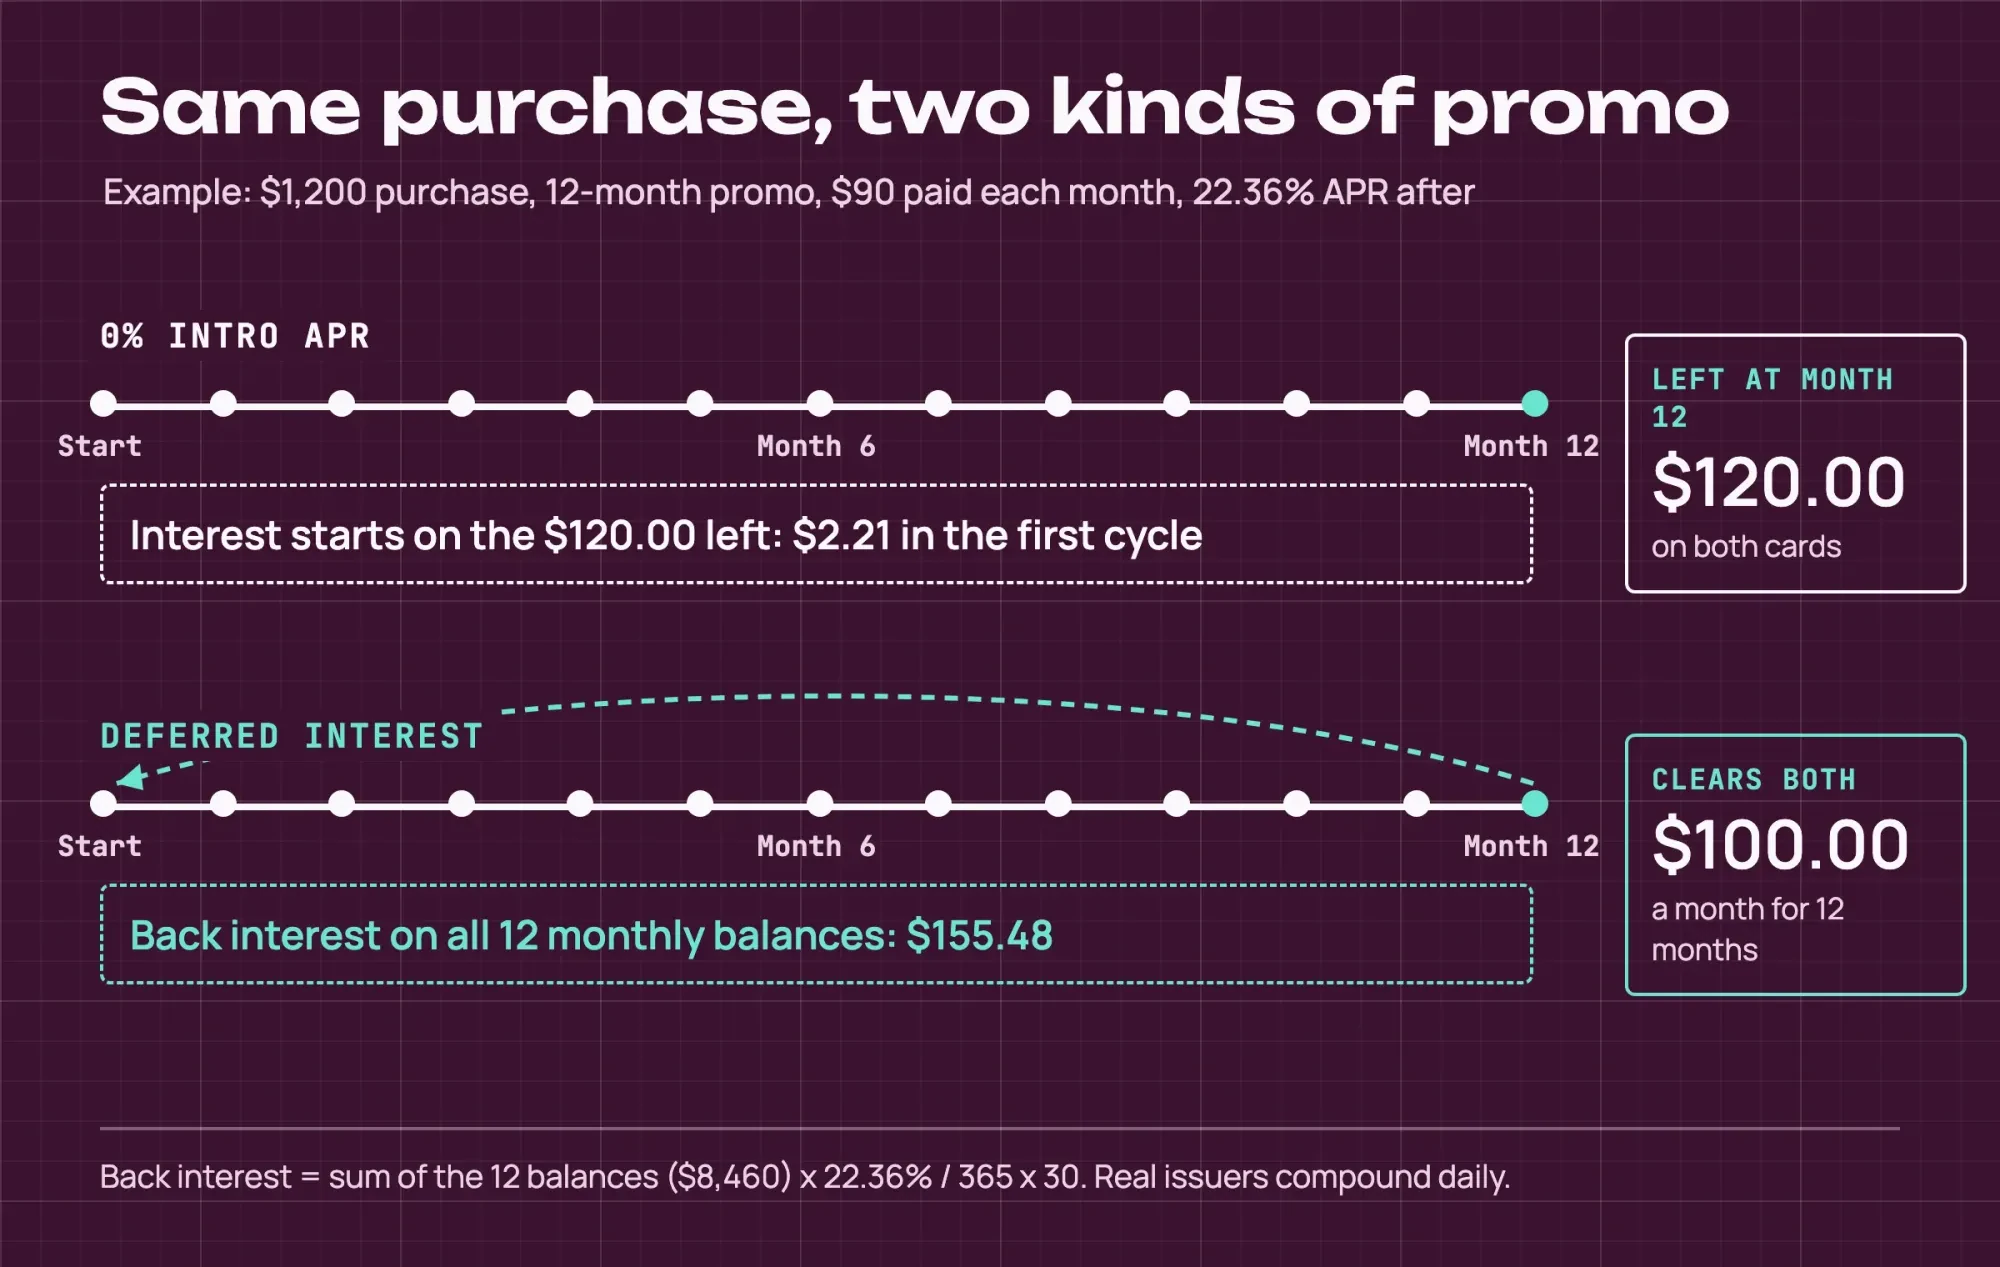 Diagram by DigitalTreed: values from our October 30, 2026 calculator run on a made-up $1,200 purchase; rules from 12 CFR 1026.16(h) and the CFPB.
Intro rates also come with a floor on their length. Under 15 U.S.C. 1666i-2, a promotional rate can't rise "before the end of the 6-month period" after it starts. 12 CFR 1026.55(b)(1) puts it as "a specified period of six months or longer."
The CFPB's answer on intro rate length names one exception, a payment more than 60 days late, and adds that a variable intro rate can still follow its index.
Where a payment above the minimum goes
Many cards carry balances at different rates at the same time, like ordinary purchases plus a cash advance that started charging interest the day it was taken. For those, 12 CFR 1026.53(a) sets the order. The issuer "must allocate the excess amount first to the balance with the highest annual percentage rate." Whatever's left goes to the others "in descending order based on the applicable annual percentage rate." The rule came from the Credit CARD Act of 2009, approved May 22, 2009, where section 104 carries the title "Application of card payments." Today the same order sits in 15 U.S.C. 1666c.
The minimum's a different story. The CFPB's answer on balances at different APRs puts it this way. "It is generally up to the card issuer to decide to which balance it will apply the minimum amount portion of your total payment."
Our example card had $1,500 of purchases at 22.36% and a $500 cash advance at a made-up 29.99%, with a $45 minimum. We assumed the issuer put the minimum on purchases. The rule then sent the $255.00 above it to the cash advance. That left $1,455.00 of purchases and $245.00 of cash advance, and next cycle's interest came to $32.78. Had all $300 gone to purchases, it'd have been $34.38, or $1.60 more. That's small for one month. It repeats every cycle the cash balance lasts, though. Your statement must show each APR and the balance at each rate, the CFPB notes, so the same check works on a real bill.
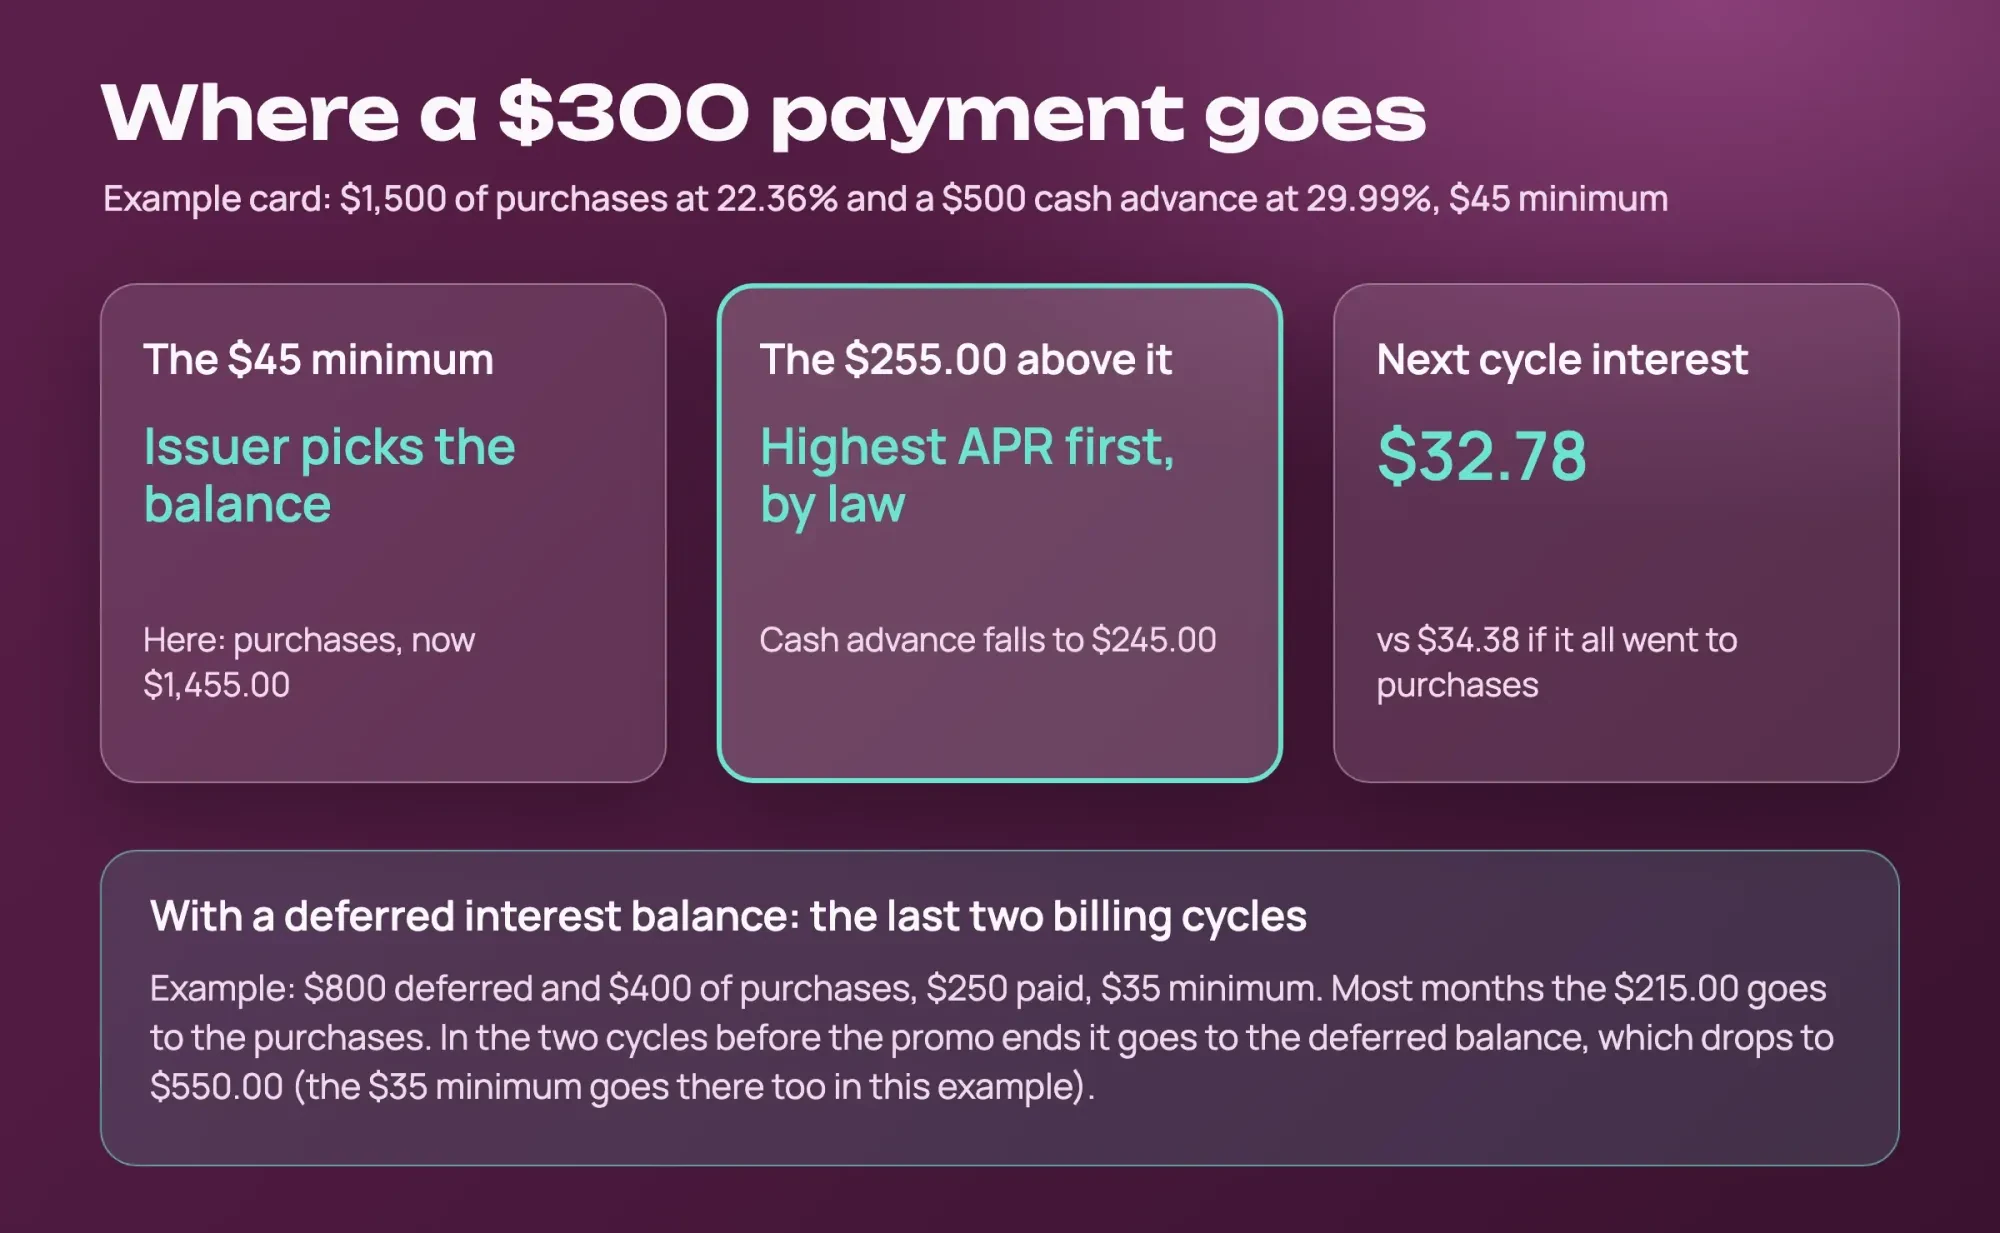 Diagram by DigitalTreed: made-up balances and APRs; allocation order from 12 CFR 1026.53 and 15 U.S.C. 1666c.
Deferred interest flips the order near the end. In most months, the extra goes to higher-rate balances first, the CFPB's deferred interest page says. During "the two billing cycles immediately preceding expiration," though, 1026.53(b) sends the excess to the deferred balance first. The CFPB's page says the same in plain terms: at that point, your card issuer "must use that money to pay down your deferred interest purchases." In our example, $800 was deferred with $400 of purchases, and $250 was paid against a $35 minimum. Those last two cycles put the $215.00 on the promo balance. Our example also applied the $35 minimum there, so it fell to $550.00 ($800 - $35 - $215).
On an account with a deferred interest balance, 1026.53(b)(1)(ii) also lets an issuer split your payment the way you ask, but only "at its option."
Credit card financing questions
Frequently asked
When is a credit card payment late?
Under 12 CFR 1026.10, the cut-off can't be earlier than 5 p.m. on the due date. If the issuer takes no mail that day, a mailed payment is on time the next business day, as the CFPB's late payment answer also says.
Does a 0% balance transfer stop interest on new purchases?
No. The CFPB's balance transfer answer says that while you carry a balance, purchases "will accrue interest from the date of the transaction."
Is carrying $500 on a card cheaper than a payday loan?
In our calculator, $500 at 22.36% for 70 days costs $21.44. Our payday lender check shows $375 in fees on $500 over ten weeks, from the FTC's $15 per $100 example.
Do I have to pay the 3-year amount in the box?
No. The CFPB says "You do not have to pay any more than the minimum amount shown on your statement."
How we made this guide: Rules come from Regulation Z, the U.S. Code and CFPB pages, and the rate from the Federal Reserve. Facts checked by the DigitalTreed team on October 30, 2026.
Before this rewrite of October 30, 2026, the page listed card habits with survey numbers we couldn't trace. Those numbers are gone, and the federal rules and our own math replace them. A card payment more than 60 days late can also end an intro rate early, as covered above. For a bill that's already past due, our list of what to try when an emergency bill lands puts the options in order.
Sources
- Federal Reserve: G.19 Consumer Credit, release of October 7, 2026
- FRED: Commercial bank interest rate on credit card plans, accounts assessed interest
- eCFR: 12 CFR 1026.5, General disclosure requirements
- eCFR: 12 CFR 1026.7, Periodic statement
- eCFR: 12 CFR 1026.10, Payments
- eCFR: 12 CFR 1026.16, Advertising
- eCFR: 12 CFR 1026.53, Allocation of payments
- eCFR: 12 CFR 1026.54, Limitations on the imposition of finance charges
- eCFR: 12 CFR 1026.55, Limitations on increasing annual percentage rates
- 15 U.S.C. 1637: Open end consumer credit plans (govinfo)
- 15 U.S.C. 1643: Liability of holder of credit card (govinfo)
- 15 U.S.C. 1666b: Timing of payments (govinfo)
- 15 U.S.C. 1666c: Prompt and fair crediting of payments (govinfo)
- 15 U.S.C. 1666i-2: Additional limits on interest rate increases (govinfo)
- Public Law 111-24: Credit CARD Act of 2009 (govinfo)
- CFPB: What is a credit card interest rate? What does APR mean?
- CFPB: What is a daily periodic rate on a credit card?
- CFPB: How does my credit card company calculate the amount of interest I owe?
- CFPB: What is a grace period for a credit card?
- CFPB: If I pay off my balance when it is due, can I be charged interest for that month?
- CFPB: Do I pay interest on new purchases after a zero or low rate balance transfer?
- CFPB: The three-year payment box on a credit card bill
- CFPB: Different APRs on one bill
- CFPB: No interest if paid in full within 12 months, how does this work?
- CFPB: How long can I keep a low introductory rate?
- CFPB: Unauthorized charges on a lost or stolen credit card
- CFPB: When is my credit card payment considered late?
Comments
No comments yet. Start the conversation below.